
Calculation
true range TR = max(high − low, |high − previous close|, |low − previous close|)
ATR = RMA(TR, 14)            Wilder's smoothing, α = 1/14, started from a simple average
Including the previous close makes gaps count: a stock that gaps 5% and then trades in a narrow range still has a large true range.
How to read it
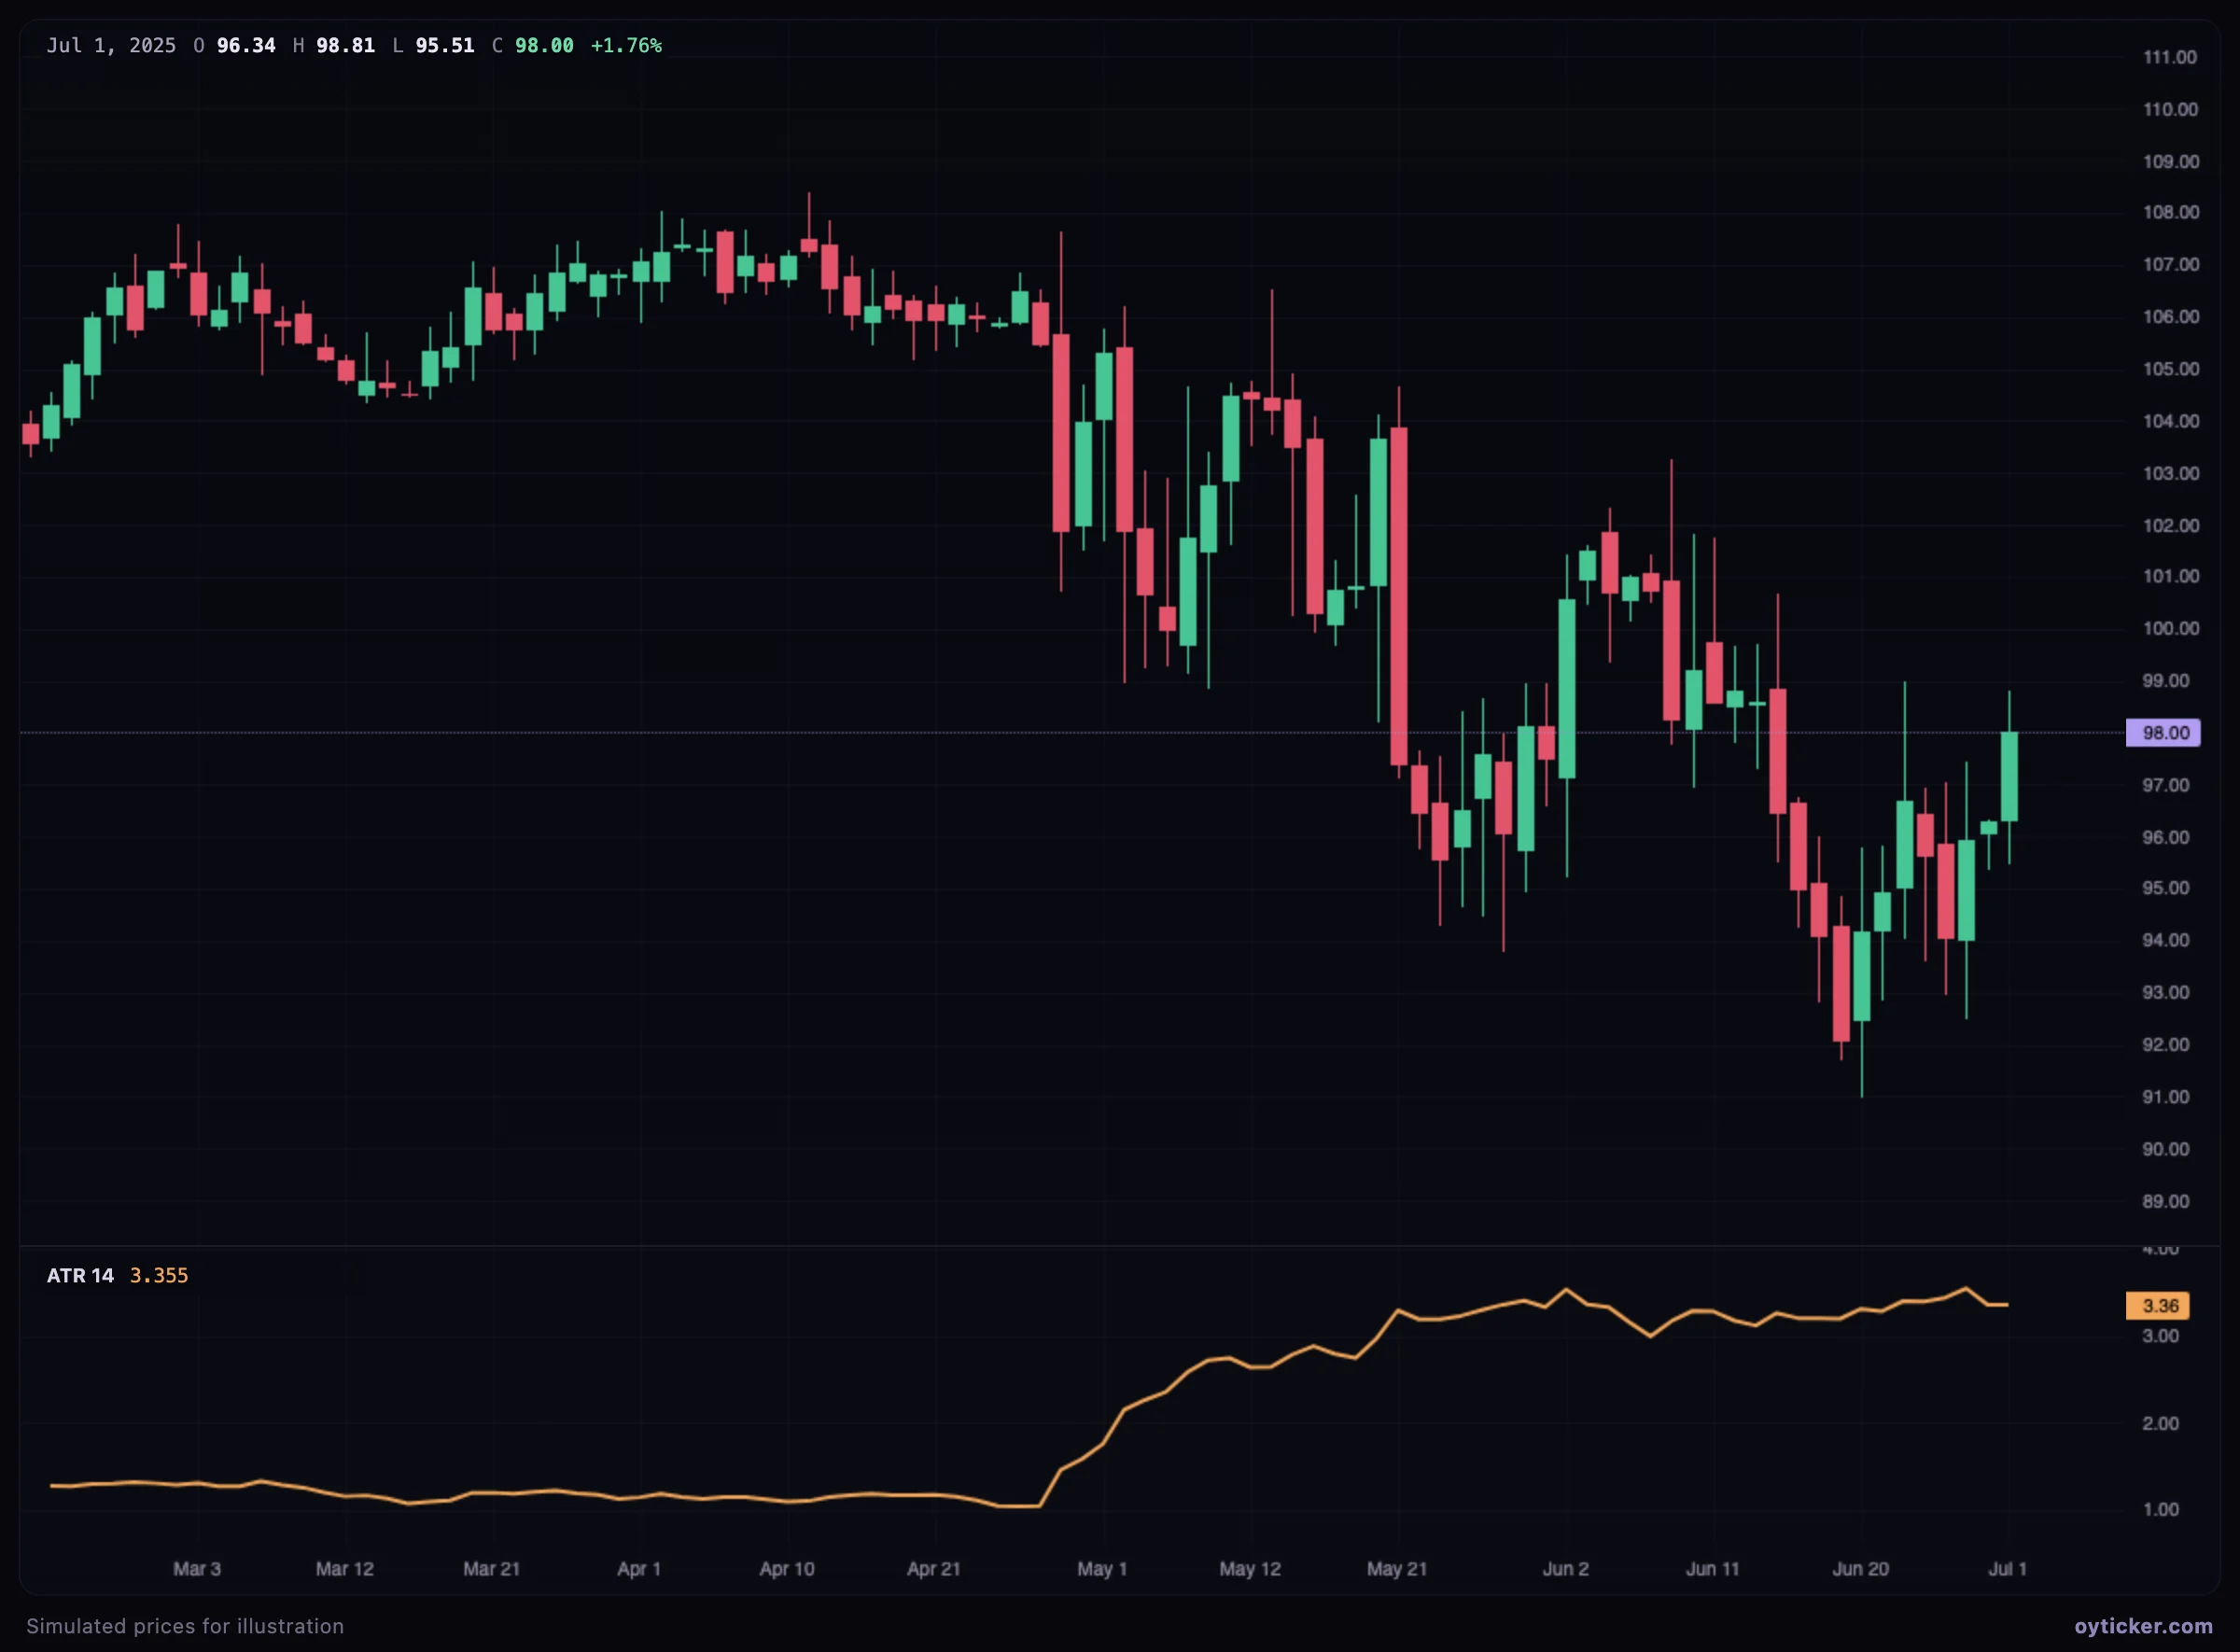
- Stops: a stop 1.5 to 3 ATR away from the entry sits outside normal noise. Oyticker's position tools place the default stop one ATR away.
- Position size: for a fixed risk per trade, a higher ATR means a smaller position.
- Regimes: rising ATR during declines and falling ATR in quiet advances is typical of equities.
Limits
ATR is in price units: compare it between assets (or across a large price change) in percent of the price, ATR / close.
Charts in this guide use simulated prices generated for illustration; levels and outcomes shown are examples, not observations of a real market. Educational content only, not investment advice.